The Rise of the Tech Giants
Abstract
In less than three decades, five companies, Amazon, Apple, Alphabet (Google), Meta (Facebook), and Microsoft, built a digital infrastructure through which a large share of economic and social life flows. Their first moat was the network effect: platforms become more valuable the more people use them. Two later layers mattered as much. Three of the five rent out the cloud servers other companies run on, and since 2022 the race for generative AI has turned compute into a barrier to entry, and Nvidia, the supplier of the chips, became in 2025 the first company worth $5 trillion. TikTok showed that the social-network moat could be bypassed. Regulators came late: the EU’s Digital Markets Act took effect in 2023, and between 2024 and 2026 US courts found Google to be a monopolist twice but declined to break it up, and cleared Meta. Its figures and rankings reflect the state of play when it was last reviewed, in September 2026.
Five Companies, One Infrastructure
“Big Tech” is not an industry in the classical sense. Amazon sells goods, cloud computing and streaming; Apple makes hardware; Google runs search and sells advertising; Meta operates social networks; Microsoft supplies operating systems and office software. What they share is their function as platforms: each controls the infrastructure through which millions of other products and services reach their customers.
- Amazon runs the largest cloud business, AWS, and a Marketplace that sets the terms under which merchants worldwide sell.
- Apple reported more than 2.5 billion active devices in January 2026, and the App Store is the main channel for native iPhone software; alternative app stores exist only where laws such as the EU’s Digital Markets Act require them.
- Alphabet/Google handles about 90 percent of general search queries in the United States, the figure the court accepted in United States v. Google, which makes it the main gateway to information and advertising.
- Meta counted 3.6 billion people using at least one of Facebook, Instagram, Messenger or WhatsApp on an average day in June 2026.
- Microsoft dominates workplace software through Windows and Office, runs the second-largest cloud, owns GitHub, and holds 27 percent of OpenAI.
In May 2023 Michael Hartnett, an investment strategist at Bank of America, grouped Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla as the “Magnificent Seven”, after the 1960 western. Those seven stocks produced more than half of the S&P 500’s total return in 2023 and again in 2024. Two of the seven, Nvidia and Tesla, were not platforms in the sense above, and the list marks how the ranking changed once AI arrived.
The Network Effect as Moat
The theoretical foundation of this power was sketched by Robert Metcalfe around 1980: the value of a network grows with the square of the number of participants (Metcalfe’s Law). A telephone that can only call itself is worthless; a telephone in a network of a billion devices is indispensable.
Platform economists distinguish two variants:
- Direct network effects: every new Facebook user makes Facebook more attractive to all existing users, because more people become reachable.
- Indirect network effects: more iPhone users motivate more developers to build apps, which in turn attracts more users. More Amazon buyers motivate more merchants, which improves selection and attracts still more buyers.
Platform monopoly and production monopoly
An oil producer with a monopoly controls a resource. A platform monopolist controls a relationship: between buyers and sellers, users and developers, advertisers and audiences. Traditional antitrust analysis measures harm by consumer prices, and many platform services cost the user nothing. The user pays with attention and data, and the paying customer is the advertiser.
Whoever wins a network-effect market once tends to keep it, because users face switching costs: moving years of photos out of iCloud, persuading every contact to change messaging apps, or giving up an established Amazon review history as a merchant. That friction holds users inside an ecosystem even when a better alternative exists.
Kill Zones and Acqui-Hires
The companies also defended their lead by buying potential rivals. Well-known examples:
| Year | Buyer | Acquisition | Price |
|---|---|---|---|
| 2006 | YouTube | ~1.65B USD | |
| 2012 | Meta | 1B USD | |
| 2014 | Meta | ~19B USD | |
| 2014 | Meta | Oculus VR | ~2B USD |
| 2016 | Microsoft | 26.2B USD | |
| 2017 | Amazon | Whole Foods | 13.7B USD |
| 2018 | Microsoft | GitHub | 7.5B USD |
| 2023 | Microsoft | Activision Blizzard | ~69B USD |
Two patterns stand out. Killer acquisitions take out startups before they mature into competitors. Facebook bought Instagram in 2012, when the app had 13 employees, no revenue and 30 million users on the phones where Facebook’s own app was weak. Mark Zuckerberg wrote internally that Instagram “can hurt us meaningfully.” Acqui-hires target the engineering team rather than the product, which is often shut down after the deal.
Researchers call the result a kill zone. Sai Krishna Kamepalli, Raghuram Rajan and Luigi Zingales (University of Chicago, 2020) studied nine acquisitions by Google and Facebook between 2006 and 2016, including YouTube, Instagram and WhatsApp. In the three years after each deal, venture capital investment in startups in the same space fell by 46 percent and the number of deals by 42 percent.
The AI boom produced a variant that avoids merger review altogether, the reverse acqui-hire: the large company licenses a startup’s technology, hires its founders and most of its staff, and leaves the company itself standing. Microsoft paid Inflection AI about $650 million in March 2024 and hired its chief executive, Mustafa Suleyman, to run its consumer AI unit. Google paid about $2.7 billion in a licensing deal with Character.AI in August 2024 and rehired its founder Noam Shazeer, a former Google engineer; the Justice Department examined whether the structure was meant to escape merger review. Meta put about $14 billion into Scale AI for a 49 percent stake in June 2025 and hired its chief executive, and Google paid $2.4 billion for a license and the leaders of the coding startup Windsurf in July 2025. Because no company changed hands, none of these deals needed the approval that a purchase of the same size would have.
The Interest Graph
The network-effect theory predicted that no newcomer could build a social platform against Facebook, since users go where their friends already are. TikTok did it without a friend network. Its default screen, the “For You” feed, shows short videos chosen by a recommendation model from what each user watches, skips and replays, mostly from accounts the user does not follow. Industry writers called it an interest graph in contrast to Facebook’s social graph. A new user gets a useful feed within minutes and does not need to bring any friends along.
The incumbents rebuilt their products around the same model. Instagram launched Reels in August 2020, and YouTube began testing Shorts in India the following month. On Meta’s earnings call in July 2022 Zuckerberg said that about 15 percent of the content in a Facebook user’s feed came from accounts the user did not follow, recommended by AI, a bit more on Instagram, and that he expected the share to more than double by the end of 2023. When the FTC’s case against Meta came to judgment in November 2025, the court used the same shift against the government: Judge James Boasberg found that people treated TikTok and YouTube as substitutes for Facebook and Instagram, so Meta did not hold the monopoly the FTC alleged (see below).
The interest graph did not abolish scale advantages. A recommendation model improves with every video watched, a data network effect, and TikTok grew in the West on ByteDance’s money and on the 2017 purchase of Musical.ly’s user base. Its weak point turned out to be politics rather than competition: a 2024 US law forced ByteDance to sell TikTok’s American operations, which went to a US-led joint venture in January 2026 (see ByteDance and TikTok).
The Cloud Layer
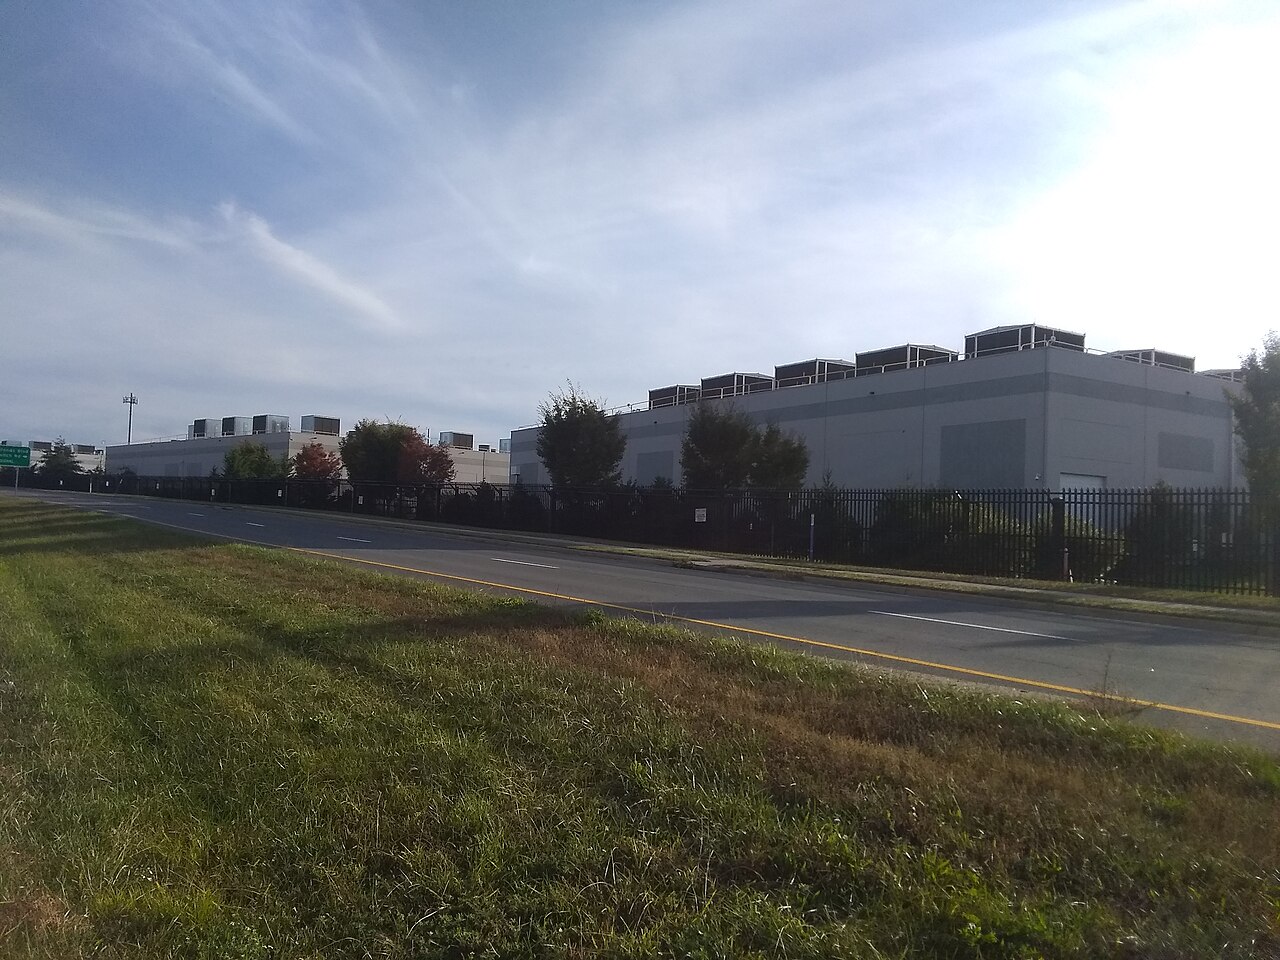
The platform power that consumers rarely see sits in business-to-business computing. Amazon opened AWS to the public in 2006; Microsoft Azure and Google Cloud followed (see The Cloud Wars and The Cloud Computing Era). In the second quarter of 2026, according to Synergy Research Group, companies spent $143 billion on cloud infrastructure services, 43 percent more than a year earlier. Amazon held 28 percent of that market, Microsoft 20 percent and Google 15 percent: 63 percent between three companies.
Cloud customers face the same switching costs as consumers, in a different form. Software written against one provider’s databases, identity systems and AI services is expensive to move, and providers charge egress fees when data leaves their network. The dependence becomes visible when something breaks. Shortly before midnight Pacific time on October 19, 2025, a race condition in the automation that manages DNS records for DynamoDB, a database service in AWS’s northern Virginia region (us-east-1), left the service’s address empty. The database fault itself lasted about three hours, but other AWS services that depended on it failed in turn, and full recovery took until the afternoon of October 20. Messaging apps, banks, airlines, games and smart doorbells went down with it, for users on several continents who had never heard of the region.
The EU’s competition authority opened market investigations into AWS and Azure under the Digital Markets Act in November 2025. In June 2026 it announced its preliminary view that both should be designated gatekeepers, as the largest and second-largest cloud services in the EU, even though neither met the law’s numerical thresholds.
Compute as a Moat
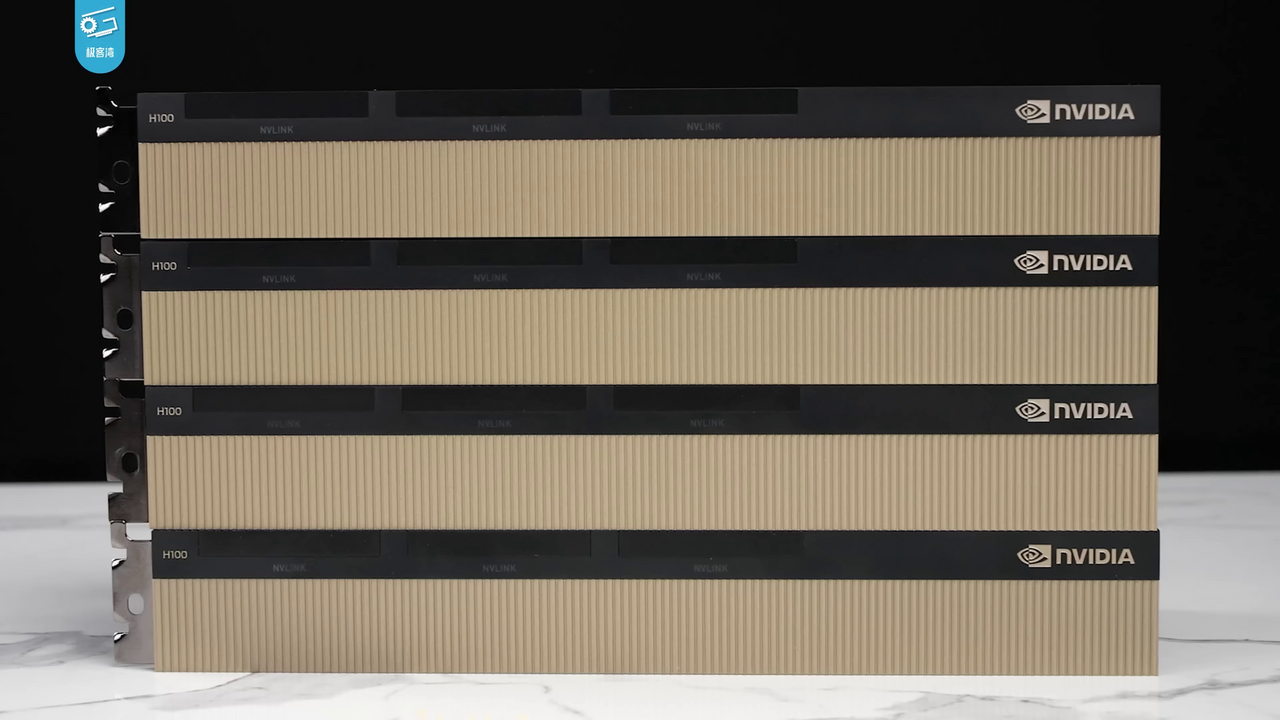
ChatGPT’s release in November 2022 (see The LLM Race) added a new barrier to entry. Training a frontier language model takes tens of thousands of specialized chips, data centers to hold them and the electricity to run them. Microsoft, Alphabet, Amazon, Meta and Oracle spent about $380 billion on capital expenditure in 2025, most of it for AI infrastructure, and in February 2026 their plans for the year added up to between $660 and $690 billion. Meta alone expected to spend $130 to $145 billion in 2026, more than its entire revenue in 2021.
The chips came overwhelmingly from Nvidia, whose data-center GPUs and CUDA software had become the standard tools of machine learning. Its data-center revenue rose to $193.7 billion in the fiscal year that ended in January 2026, out of total revenue of $215.9 billion. Nvidia passed a market value of $4 trillion in July 2025 and, on October 29, 2025, became the first company worth more than $5 trillion. The largest customers were the same platform companies, which also began designing their own accelerators (Google’s TPU, Amazon’s Trainium, Microsoft’s Maia) to reduce the dependence (see Jensen Huang and Nvidia).
The new AI labs did not escape the incumbents. They depended on them for money and compute, and much of the money came back as cloud spending. Microsoft invested more than $13 billion in OpenAI; when OpenAI converted into a public benefit corporation in October 2025, Microsoft kept a 27 percent stake, and OpenAI committed to buy another $250 billion of Azure services. Anthropic took its largest investments from Amazon and Google and trained its models largely on their clouds. Google trained its Gemini models on its own TPUs.
Antitrust in the United States
For two decades the US government did little. The last major technology case, United States v. Microsoft (1998–2001), had ended with Judge Thomas Penfield Jackson ordering Microsoft’s breakup in 2000; an appeals court overturned the order in 2001, and the case was settled with behavioral remedies. The acquisitions of the 2000s and 2010s went through: the FTC cleared the Instagram purchase in 2012 without conditions. In February 2020 the FTC ordered the five companies to report acquisitions that had fallen below the mandatory filing thresholds. Its 2021 report counted 616 such deals between 2010 and 2019. The Biden administration’s Executive Order on Promoting Competition (July 2021) signaled a harder line.
Then the cases came to court (see The Platform Antitrust Story):
- Search. In United States v. Google, filed in October 2020, Judge Amit Mehta ruled on August 5, 2024: “Google is a monopolist, and it has acted as one to maintain its monopoly.” The evidence centered on the payments that made Google the default search engine on Apple devices, Android phones and browsers, $26.3 billion in 2021 alone. The remedies came on September 2, 2025. Mehta refused the government’s request to force the sale of Chrome, allowed Google to keep paying for default placement as long as the contracts were not exclusive, and ordered it to share parts of its search index and user-interaction data with qualified competitors for six years. He wrote that the rise of generative AI had “changed the course of this case”, since chatbots were becoming a new route into search. Google appealed the liability finding. The government cross-appealed in February 2026, but its brief in July dropped the demand for Chrome and asked the appeals court for a ban on the default-placement payments instead.
- Advertising technology. In a second case, Judge Leonie Brinkema ruled on April 17, 2025, that Google had illegally monopolized the publisher ad-server and ad-exchange markets for open-web display advertising and tied the two together. Her remedies, ordered on September 2, 2026, again stopped short of a sale: Google keeps its AdX exchange and DFP ad server but must open them to rival tools and accept a court-appointed monitor for six years.
- Social networking. The FTC’s case against Meta, filed in December 2020 to undo the Instagram and WhatsApp purchases, went to trial in April 2025. On November 18, 2025, Judge Boasberg ruled that the FTC had not shown that Meta currently held a monopoly, because the market now included TikTok and YouTube. The FTC appealed.
- Smartphones. In March 2024 the Justice Department and a group of states sued Apple, accusing it of keeping its smartphone monopoly through restrictions on messaging, smartwatches, digital wallets and “super apps”, the ecosystem lock-in described above. Judge Julien Neals refused to dismiss the case in June 2025 and set a schedule pointing to a trial no earlier than 2027.
- Retail. The FTC and 17 states sued Amazon in September 2023 over the treatment of Marketplace sellers, including penalties for offering lower prices elsewhere. The trial was later scheduled for March 29, 2027.
The Digital Markets Act
The broadest regulatory response came from Brussels. The Digital Markets Act (DMA) entered into force on November 1, 2022, and its rules applied from May 2, 2023. The law designates gatekeepers, platforms that other businesses cannot avoid in order to reach customers. On September 6, 2023, the European Commission designated six: Alphabet, Amazon, Apple, ByteDance, Meta and Microsoft, with a total of 22 core platform services.
Gatekeeper obligations include:
- Interoperability: messaging services like WhatsApp must be able to exchange messages with smaller competitors.
- Alternative app distribution: Apple must allow apps to be installed outside the App Store on iOS in the EU.
- Data separation: personal data from different services may not be combined without explicit consent.
- No self-preferencing: a gatekeeper may not favor its own services in rankings and search results.
Violations can be fined up to 10 percent of worldwide annual revenue, and up to 20 percent for repeat offenses. The Commission opened its first non-compliance investigations against Alphabet, Apple and Meta in March 2024. The first fines followed on April 23, 2025: €500 million for Apple, for preventing app developers from pointing users to cheaper offers outside the App Store, and €200 million for Meta, for its “consent or pay” model, which made users choose between personalized advertising and a subscription. The DMA works in advance, by rule, where US antitrust law has to prove harm case by case, and its reach is limited to the EU: Apple’s changes to app distribution applied to European users only.
Dead End: Breaking Them Up
The historical parallel critics draw most often is Standard Oil. John D. Rockefeller’s company controlled about 90 percent of US oil refining at the end of the 19th century, was accused of predatory pricing, and was split into 34 companies by the Supreme Court in 1911. Legal scholars such as Lina Khan, later chair of the FTC, argued for structural separation of platforms from the businesses that compete on them.
Where the analogy holds: Standard Oil controlled the physical pipelines of the oil market; Google controls the pipelines of online information (search, advertising, Chrome, Android). A business that cannot reach users through Google’s search results, ads or Play Store is hard for billions of people to find.
Where it fails:
- Price. Standard Oil’s critics accused it of raising prices once rivals were gone. Search, social networks and many platform services cost users nothing, and US antitrust law since the 1970s has measured harm mainly through prices paid by consumers.
- Two-sided markets. Standard Oil sold one product to one set of customers. Google serves users, who pay with data, and advertisers, who pay with money. Overcharging advertisers is harder to prove than a surcharge on kerosene.
- Innovation. Instagram was a better mobile product than Facebook’s own app in 2012. The line between winning with a better product and entrenching a monopoly is harder to draw than it was with railroad rebates.
Between 2024 and 2026 the enforcement wave tested the breakup remedy directly and it failed each time. Two judges found Google guilty of monopolization, and both chose behavioral remedies over divestiture, citing the risk and the years of appeals a breakup would bring. The FTC’s attempt to unwind Instagram and WhatsApp lost at trial. The companies these cases targeted were meanwhile spending hundreds of billions of dollars a year on AI data centers that no divested unit could have afforded.
📚 Sources
- Apple: Apple reports first quarter results (January 2026) (2.5 billion active devices, via MacRumors)
- Meta: Meta Reports Second Quarter 2026 Results (3.60 billion daily active people; 2026 capex outlook)
- U.S. News: Magnificent 7 Stocks, what they are
- Chicago Booth Review: Why Big-Tech Mergers Stifle Innovation
- CNBC: Magnificent 7 stocks responsible for more than half of the S&P 500’s 2024 gain (December 31, 2024)
- BFI Working Paper: Kill Zone (UChicago, 2020)
- CNBC: Why Facebook bought Instagram
- Wikipedia: List of mergers and acquisitions by Meta Platforms
- Mergersight: Microsoft $7.5 billion acquisition of GitHub
- CNBC: How AI “zombie” deals work at Meta and Google (August 2025) (reverse acqui-hires)
- Wikipedia: Inflection AI
- Ctech: Google’s $2.7B deal with Character.AI draws DOJ attention
- TechCrunch: Zuckerberg on AI-recommended content in Facebook and Instagram feeds (July 2022)
- Time: YouTube attempts to compete with TikTok through Shorts
- Synergy Research Group: Q2 Cloud Market Passes $143 Billion (2026)
- AWS: Summary of the Amazon DynamoDB service disruption in the Northern Virginia (US-EAST-1) region (October 2025)
- European Commission: Preliminary position that Amazon’s and Microsoft’s cloud services should be designated under the DMA (June 25, 2026)
- Futurum: AI Capex 2026, the $690B infrastructure sprint (February 2026)
- NVIDIA: Financial results for fourth quarter and fiscal 2026 (SEC filing)
- Al Jazeera: Chipmaker Nvidia hits $5 trillion valuation (October 29, 2025)
- CNBC: OpenAI completes restructure, solidifying Microsoft as a major shareholder (October 28, 2025)
- TechPolicy.Press: “Google is a monopolist” and other key points from Judge Mehta’s ruling (August 2024)
- TechPolicy.Press: Google dodges breakup in landmark antitrust ruling over its search engine (September 2025)
- Courthouse News: DOJ urges DC Circuit to beef up remedies in Google monopoly ruling (2026)
- Finviz/Benzinga: DOJ files notice of cross-appeal in Google search case (February 4, 2026)
- Al Jazeera: US judge rejects bid to break up Google’s ad business (September 2, 2026)
- CNBC: Judge finds Google holds illegal online ad tech monopolies (April 17, 2025)
- AdExchanger: Judge Brinkema’s remedies decision in the Google ad tech case (September 16, 2026)
- NPR: Judge sides with Meta in antitrust trial, will not spin off WhatsApp and Instagram (November 18, 2025)
- AppleInsider: Apple loses bid to dismiss wide-ranging DOJ antitrust case (June 30, 2025)
- Wikipedia: United States v. Apple (2024) (trial schedule)
- FTC: FTC Appeals Ruling in Meta Monopolization Case (January 2026)
- MLex: US FTC-Amazon antitrust trial pushed back to March 2027
- Wikipedia: Digital Markets Act
- EU Commission: Gatekeeper Designation (Library of Congress)
- Euronews: EU’s Digital Markets Act comes into force
- Noerr: European Commission imposes first fines under the DMA against Apple and Meta (April 2025)
- Image: AWS servers in Ashburn, group 1, 2020-10-09 1.jpg by Vahurzpu (CC BY-SA 4.0), via Wikimedia Commons
- Image: NVIDIA H100 (极客湾Geekerwan) 024.png by 极客湾Geekerwan (CC BY 3.0), via Wikimedia Commons